


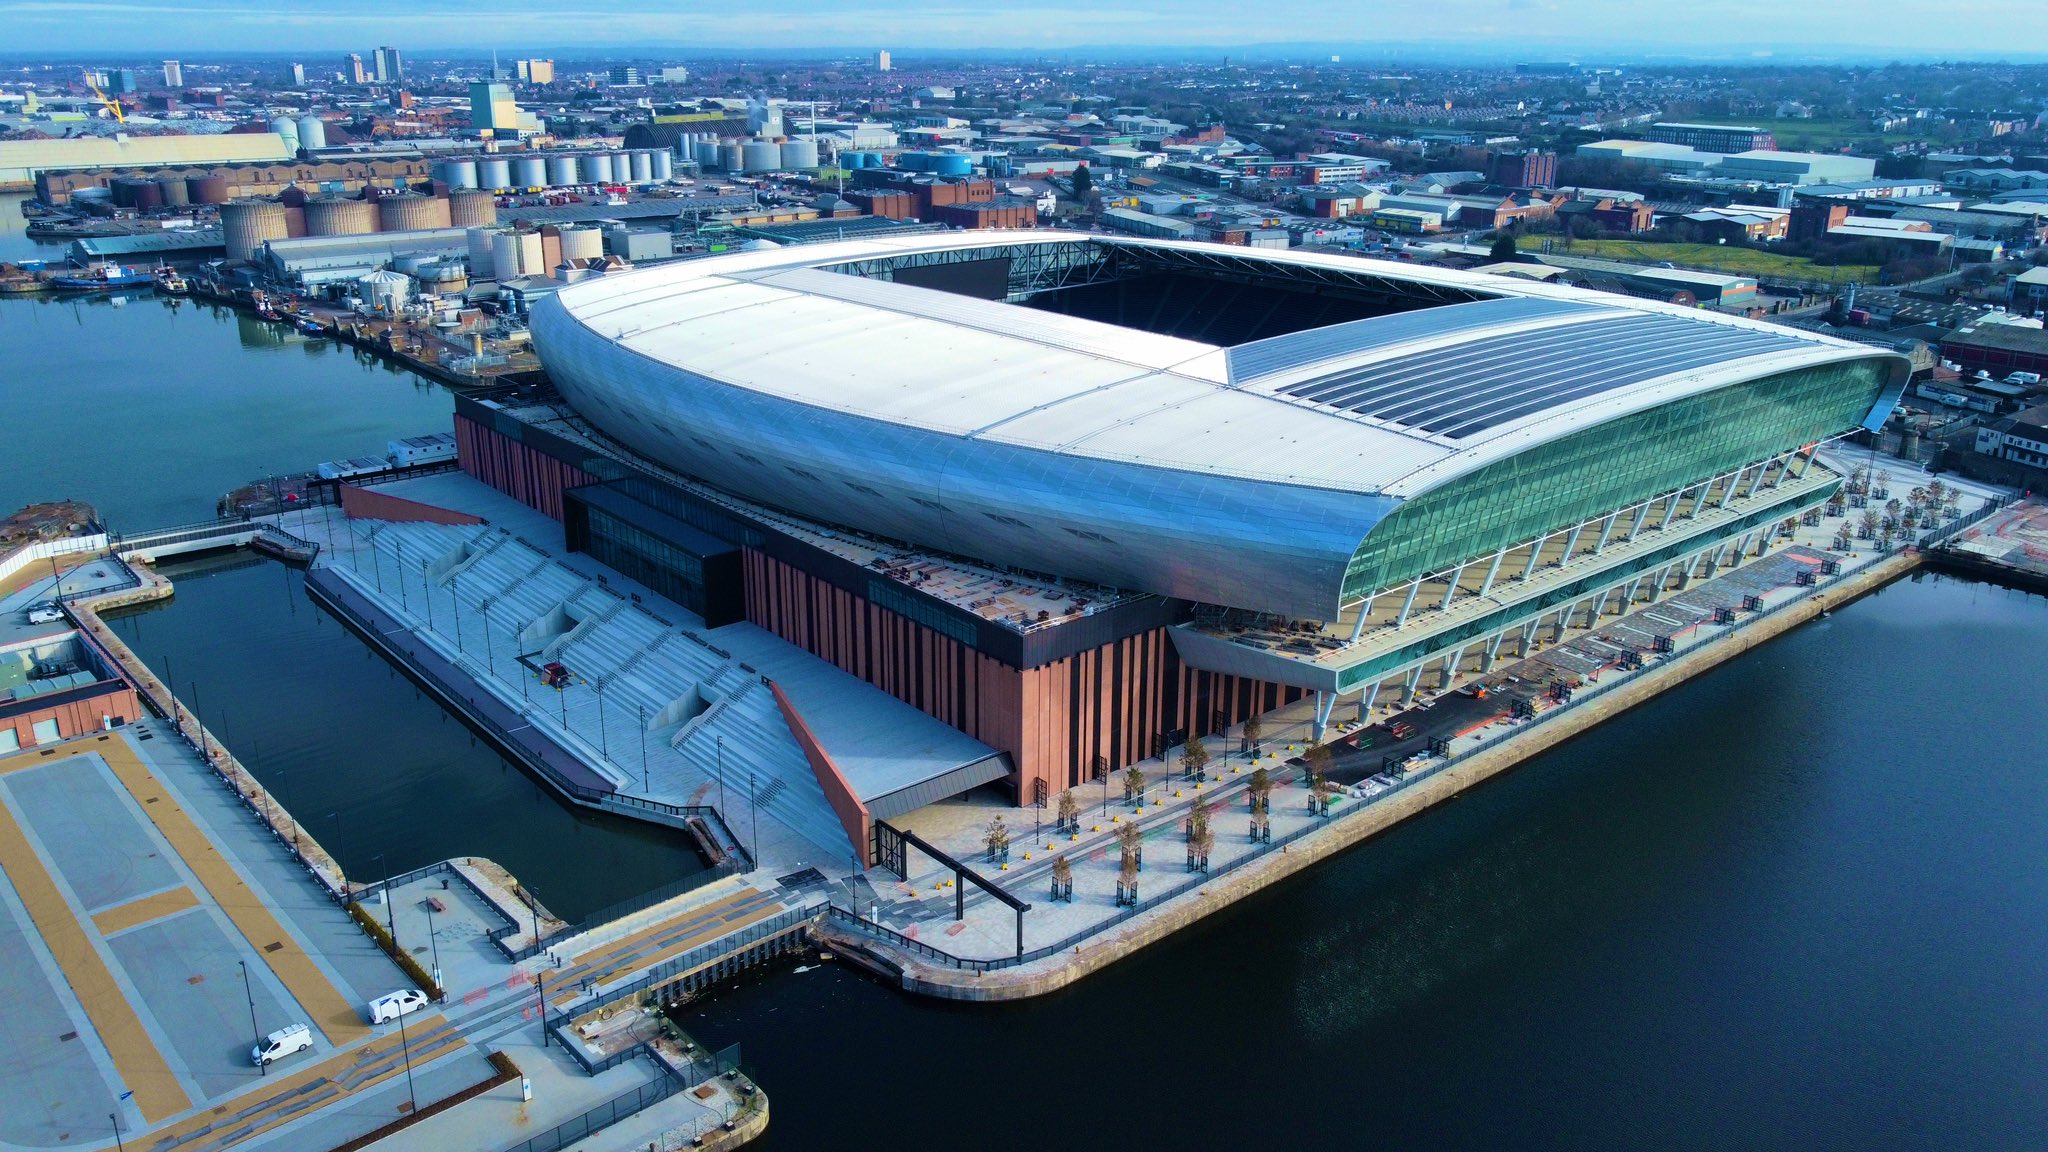
Evertonians have watched with immense pride as the magnificent new Hill Dickinson Stadium at Bramley-Moore Dock has risen from the banks of the Royal Blue Mersey. A truly transformative project for the club and the city, its completion marks the beginning of a new era.
However, amidst the excitement, questions have lingered regarding the financing of this colossal undertaking, especially given Everton’s well-documented financial struggles under Farhad Moshiri’s tenure. This in-depth analysis of Everton’s Annual Reports and Accounts aims to provide a definitive answer to the question: Where did the money really come from?
The Initial Vision and Moshiri’s Pledge
When Farhad Moshiri took over as majority Everton shareholder, the vision for a new, state-of-the-art stadium was central to his ambitious plans. Initially, Moshiri had pledged to largely self-fund the project — a commitment that seemed to offer significant reassurance to supporters considering the accountant’s widely reported wealth.
Indeed, his initial substantial injections of capital were crucial in kickstarting the development of the new stadium. In recent disclosures, Moshiri himself stated he invested £400M directly into the stadium project. This shareholder funding, often structured as interest-free loans, was a significant fiscal cornerstone for the early stages of construction.
The Shifting Sands of Funding: External Debt Becomes Crucial
The landscape of the stadium’s financing shifted dramatically, particularly following Russia’s horrific invasion of Ukraine in 2022. This geopolitical event led to sanctions against Alisher Usmanov, Moshiri’s business partner and a key Everton sponsor of Finch Farm through his USM Holdings. The loss of this significant financial backing meant Moshiri could no longer solely finance the project as initially envisioned.
As a result, Everton had to increasingly turn to external debt to continue the rapid pace of construction. The club entered into various loan agreements to bridge the funding gap. Key lenders during this period included:
-
Rights & Media Funding: This was a significant source of borrowing, secured against the club’s future media and broadcasting revenues. These loans often came with high-interest rates, a point of concern for the club’s financial health.
-
MSP Sports Capital: Another investment firm that provided substantial funding, further adding to the club’s debt pile.
-
777 Partners: This firm, which later attempted a takeover of the club that ultimately failed, also provided important loans to Everton during the stadium’s construction phase.
By 30 June 2024, the Everton Stadium Development Company Limited, the entity responsible for the project, owed over £800M. Of this, approximately £575.15M was owed to its parent company, Everton Football Club Company Limited (which included Moshiri’s shareholder loans), and £200M was a “one-year facility” secured by charges in favour of various lenders.
The capital costs incurred on the new stadium project were substantial, with the accounts showing approximately £210.9M in 2022-23 and a significant £312.7M in 2023-24. By the end of June 2024, the value of the stadium development on the balance sheet had increased from £410.6M to £730.17M. The estimated total cost for the stadium is now around £750M to £800M.
The Friedkin Group’s Intervention: Refinancing and Stability
The acquisition of Everton by The Friedkin Group in December 2024 marked a pivotal moment for the stadium’s financing. The new ownership swiftly moved to address the high-interest debt burden.
In March 2025, Everton announced a long-term £350M financing deal for the new stadium. This crucial agreement, arranged by The Friedkin Group in partnership with investment bank JP Morgan, came from a consortium of “blue-chip institutional lenders.”
The purpose of this deal was explicitly stated as refinancing the existing high-interest debt that had supported the completion of the stadium. This refinancing is expected to save the club tens of millions of pounds annually in debt repayments due to more favourable interest rates and longer repayment terms.
Furthermore, The Friedkin Group’s takeover involved a comprehensive financial restructuring. This included the conversion of Farhad Moshiri’s interest-free shareholder loans into equity, significantly strengthening the club’s balance sheet and reducing its overall debt position. All existing debt facilities were repaid as part of this process.
Beyond Debt: Commercial Growth and Future Prospects
While debt and shareholder funding have been the primary drivers, other income streams will contribute to the stadium’s long-term financial viability and indirectly to its ultimate cost recovery.
-
Commercial Partnerships: The recent agreement for Hill Dickinson to acquire the naming rights for the stadium, reportedly worth up to £10M a year (though some estimates suggest a lower figure closer to £6M plus add-ons), represents a significant new revenue stream.
-
Matchday and Other Revenue: Once operational in the 2025-26 season, the new stadium is expected to significantly boost matchday revenue due to increased capacity (recently adjusted down to 52,719) and enhanced hospitality offerings.
-
Non-Football Events: The stadium is designed as a multi-purpose venue and has already been selected as a host venue for a Rugby League Test Match against Australia in November, and Uefa’s 2028 Euros, with plans for various other events, further diversifying revenue streams.
Conclusion: A Complex Tapestry of Funding
The journey to fund Everton’s new stadium at Bramley-Moore Dock has been a complex one, reflecting the club’s challenging financial situation under its previous ownership. While Farhad Moshiri’s initial substantial investment provided the essential catalyst, the project’s completion ultimately relied on a significant accumulation of high-interest external debt.
The recent intervention of The Friedkin Group has been critical in stabilising the financial picture, primarily through a substantial refinancing package and the conversion of shareholder loans to equity. This has shifted the burden of the stadium’s cost from precarious short-term debt to a more sustainable long-term financing structure, underpinned by the new owners’ commitment and the anticipated commercial revenues from a world-class venue.
In essence, the fantastic new stadium at Bramley-Moore Dock was built through a combination of:
-
Farhad Moshiri’s significant personal investment (estimated at £400M).
-
Substantial high-interest loans from various lenders (Rights and Media Funding, MSP Sports Capital, 777 Partners), which covered the remaining majority of the construction costs as Moshiri’s direct funding diminished.
-
The Friedkin Group’s recent refinancing of this debt into a more manageable, long-term package, along with their conversion of Moshiri’s loans into equity in the form of a massive issue of new Everton shares, which has ultimately provided the long-term financial security for the stadium.
The Bramley-Moore Dock stadium stands as a testament to ambition and resilience, with its funding story serving as a stark reminder of the financial tightrope the club has walked, and the fresh start offered by the new ownership.